DR Finance India Daily
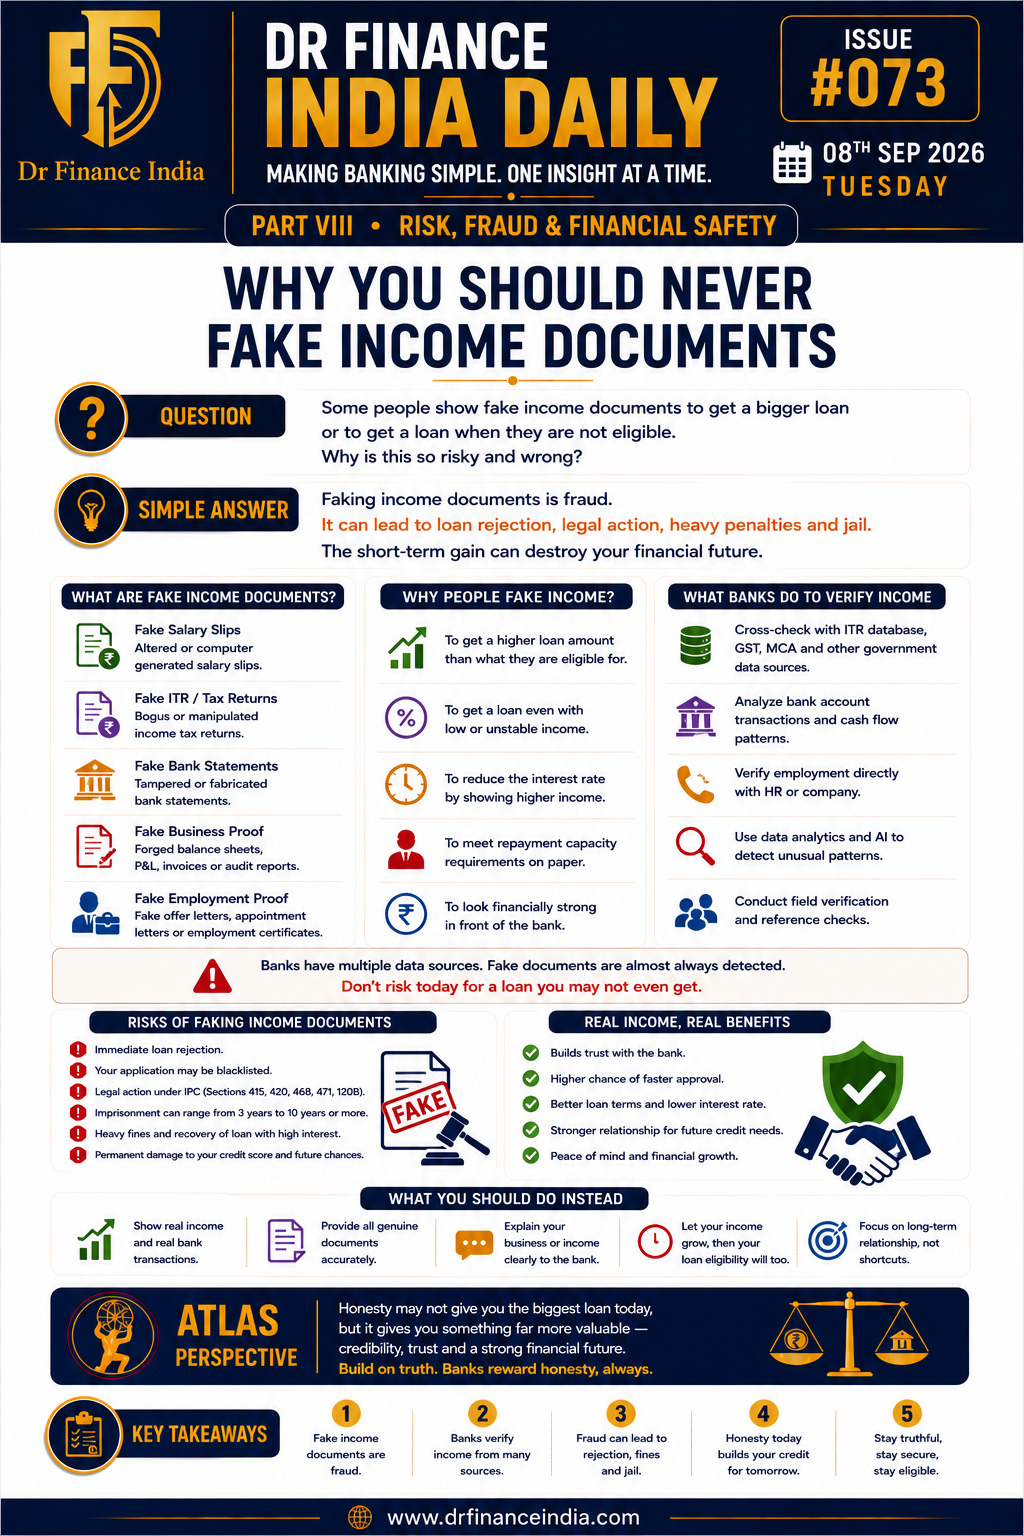
Why You Should Never Fake Income Documents
Altering income documents does not strengthen repayment capacity — it creates a false picture of it, with significant financial and legal risk.
Published by Dr Finance India · Educational content — not financial advice
Official Issue Poster
The Question
Why should you never fake income documents for a loan application?
The Simple Answer
Altering income documents does not strengthen repayment capacity — it creates a false picture of it. Lenders cross-check records against multiple sources, and discrepancies can trigger rejection or more serious consequences.
Why It Matters
Income documents help a lender understand whether the borrower can reasonably service the proposed debt. Falsifying them creates risk for the borrower that far outweighs any short-term benefit.
Detailed Explanation
Income documents help a lender understand whether the borrower can reasonably service the proposed debt. Altering those documents does not strengthen repayment capacity; it creates a false picture of it.
Examples can include fabricated salary slips, manipulated income-tax records, altered bank statements, false financial statements or inaccurate employment information. Lenders may compare these records with bank transactions, tax information, employer or business details and other available sources.
A discrepancy can trigger further verification and may result in rejection or other action depending on its nature. Even when the intention is simply to qualify for a larger loan, false documentation can create significant financial and legal risk.
Key Takeaways
- ✓Falsifying income documents creates a false picture of repayment capacity.
- ✓Lenders cross-check records against bank transactions, tax data and employer details.
- ✓Discrepancies can trigger further verification, rejection or legal action.
- ✓The risk to the borrower far outweighs any short-term benefit.
- ✓A realistic loan amount or preparation period is a safer alternative.
Borrower Takeaway
Present your actual income and financial position. If eligibility is insufficient, consider a realistic loan amount, longer preparation period or another legitimate structure rather than falsifying records.
Atlas Perspective
Present your actual income and financial position honestly. If eligibility is insufficient today, a realistic loan amount or a structured preparation period is a far safer path than falsifying records.
Share This Insight