DR Finance India Daily
What Is Debt Service Coverage Ratio (DSCR)?
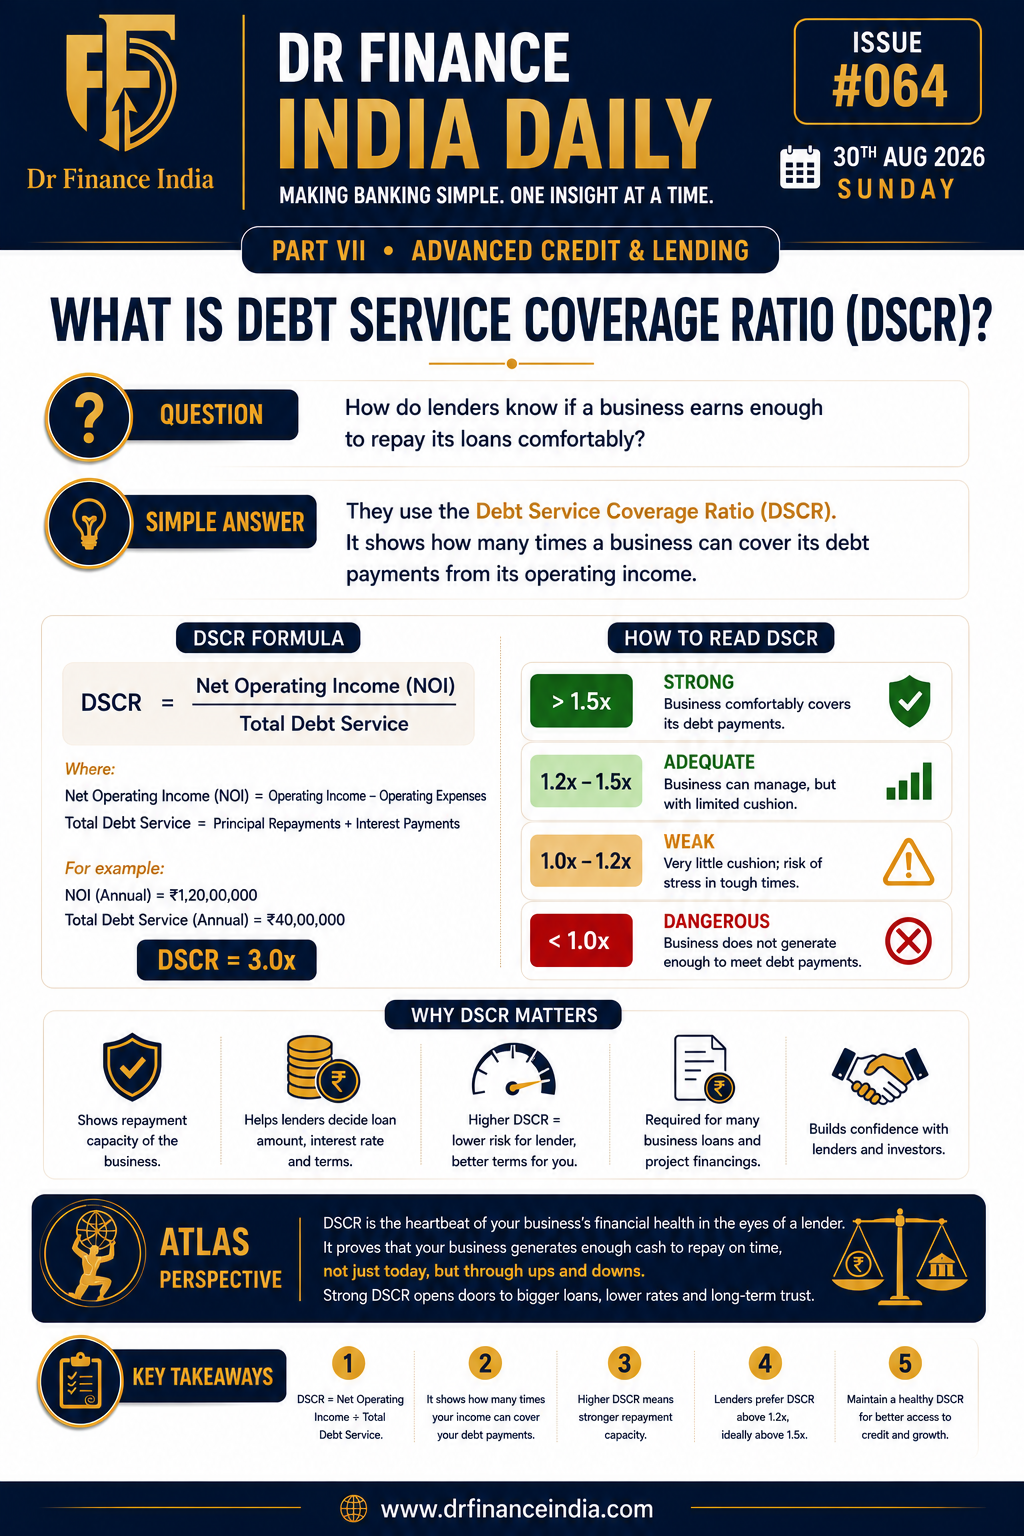
DSCR measures whether a business generates enough cash to service its debt obligations — a critical metric in business and project lending.
Official Issue Poster
The Question
How do lenders know if a business earns enough to repay its loans comfortably?
The Simple Answer
They use the Debt Service Coverage Ratio (DSCR). It shows how many times a business can cover its debt payments from its operating income.
Why It Matters
Shows repayment capacity of the business. Helps lenders decide loan amount, interest rate and terms. Higher DSCR means lower risk for lender, better terms for you. Required for many business loans and project financings. Builds confidence with lenders and investors.
Detailed Explanation
Debt Service Coverage Ratio, or DSCR, is commonly used in business and project lending to understand whether the cash generated by a business is sufficient to service its debt obligations.
In simple terms, DSCR compares cash available for debt servicing with the required principal and interest payments. A ratio above 1 indicates that available cash exceeds the measured debt service, while a ratio below 1 indicates a shortfall under that calculation.
The exact formula, period considered and acceptable level can vary by lender and type of financing. Banks may also examine projected DSCR, average DSCR and other cash-flow measures rather than relying on one standalone figure.
Key Takeaways
- ✓DSCR = Net Operating Income ÷ Total Debt Service.
- ✓It shows how many times your income can cover your debt payments.
- ✓Higher DSCR means stronger repayment capacity.
- ✓Lenders prefer DSCR above 1.2x, ideally above 1.5x.
- ✓Maintain a healthy DSCR for better access to credit and growth.
Borrower Takeaway
Strong sales alone do not prove repayment capacity. Sustainable operating cash flow, realistic projections and manageable debt commitments are critical when a lender evaluates a business loan.
Atlas Perspective
DSCR is the heartbeat of your business's financial health in the eyes of a lender. It proves that your business generates enough cash to repay on time, not just today, but through ups and downs. Strong DSCR opens doors to bigger loans, lower rates and long-term trust.