DR Finance India Daily
Why the Cost of Deposits Matters to a Bank?
The interest banks pay on deposits affects their cost of funds, loan pricing, interest spread, Net Interest Margin and overall profitability.
Published by Dr Finance India · Educational content — not financial advice
Official Issue Poster
The Question
Why does the cost of deposits matter to a bank?
The Simple Answer
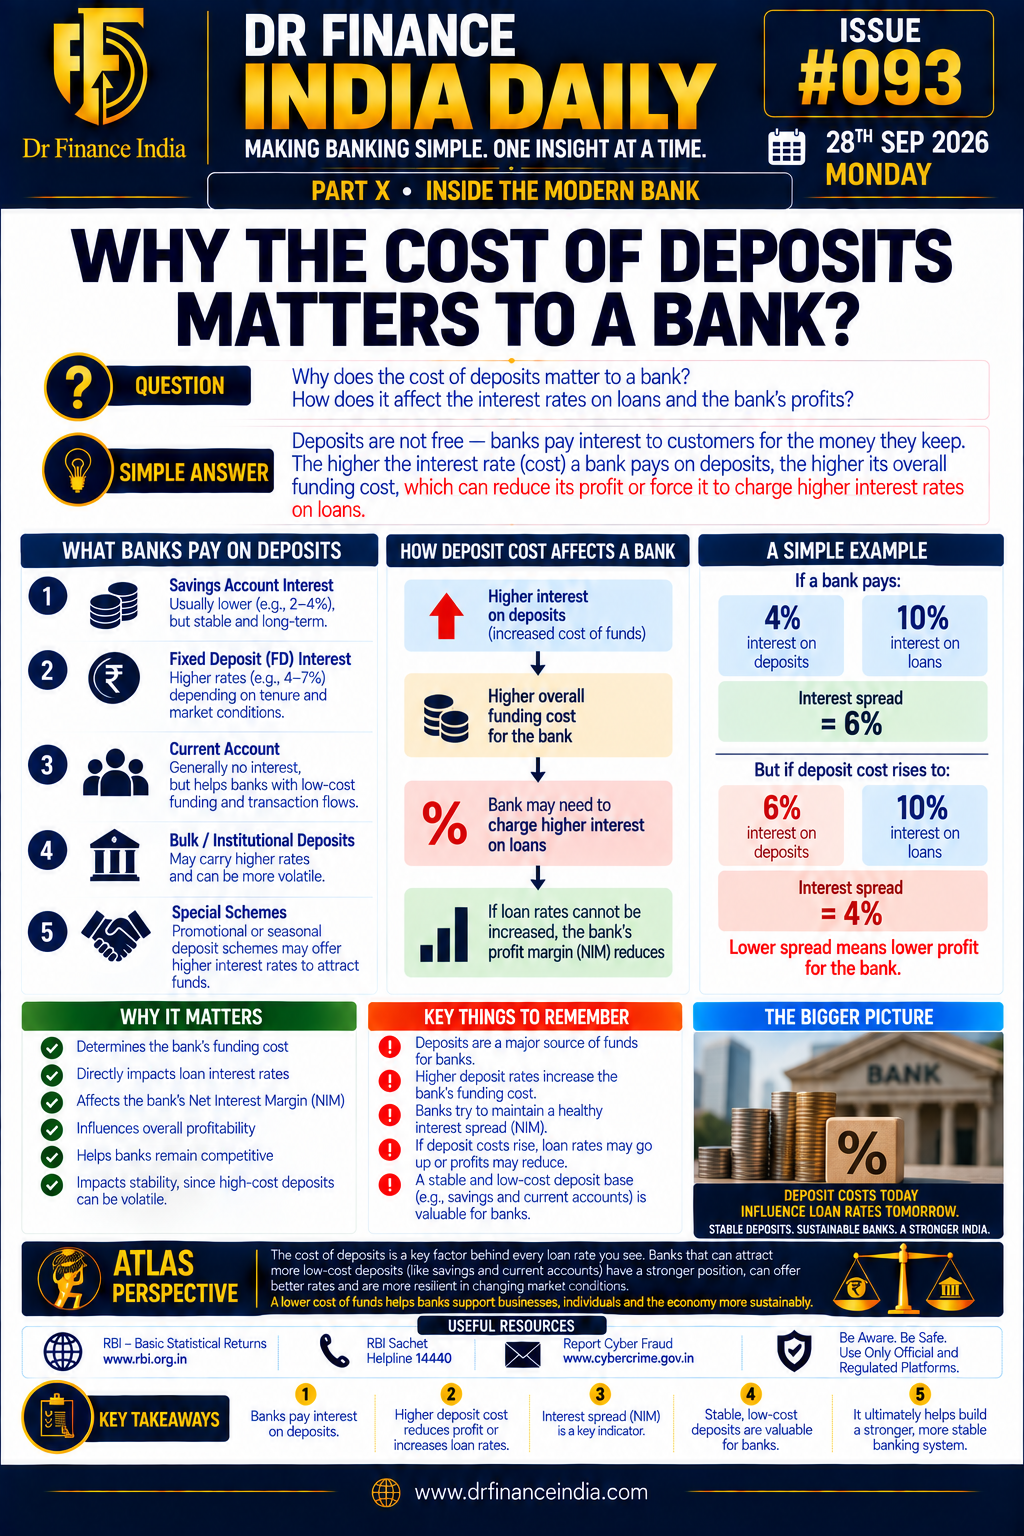
Deposits are funding for a bank, and much of that funding has a cost. When the average cost of deposits rises, the bank's overall cost of funds can rise as well, placing pressure on the interest spread and Net Interest Margin if lending yields do not increase sufficiently.
Why It Matters
Deposit rates and loan rates are connected through a bank's funding economics — understanding this helps borrowers see why rates move together.
Detailed Explanation
Deposits are funding for a bank, and much of that funding has a cost. Banks may pay interest on savings and term deposits, while current accounts generally provide very low-cost transactional funding.
When the average cost of deposits rises, the bank's overall cost of funds can rise as well. If lending yields do not increase sufficiently, the interest spread and Net Interest Margin can come under pressure.
This is why banks compete not only for deposits, but also for the right mix of deposits. Stable, granular and relatively low-cost funding can strengthen profitability and liquidity.
Key Takeaways
- ✓Most deposits have a cost — savings and term deposits pay interest.
- ✓Rising deposit costs increase a bank's overall cost of funds.
- ✓Pressure on the interest spread reduces Net Interest Margin.
- ✓Banks compete for the right mix of deposits, not just volume.
- ✓Deposit rates and loan rates are connected through funding economics.
Borrower Takeaway
Deposit rates and loan rates are connected through a bank's funding economics. A higher cost of deposits can place pressure on margins and may influence the rates banks charge borrowers.
Atlas Perspective
Deposit rates and loan rates are connected through a bank's funding economics. A higher cost of deposits can place pressure on margins and may influence the rates banks charge borrowers.
Share This Insight
Related Issues